“Divorce is Not for Wimps” is about the realities of divorce and how it too often leads to painful and long-term emotional, financial, social, and parenting consequences. Unless you’re made of steel, pain in divorce is unavoidable. Long-term trauma can be mitigated if you assume the position of a winner or champion in your divorce. There is, of course, no true winning in divorce but there is surviving, mitigating damage, and putting you and your family on track for a better future.
Whichever end you’re on—initiator or responder—you need to decide that divorce will not define you. At the same time, it’s going to be a dominant force in your life for a bit. That bit of time may be short or quite long depending on your circumstances and how you manage the process.
So, what are the essential steps?
Acknowledge that you can’t do it alone. Build your support team. Initially, it might be your best friend and sister or mother. But don’t stop there! Your best friend can’t fix this for you—they don’t have the skills or knowledge.
Build your divorce team. You need emotional, psychological, financial, and “legal” help. A divorce coach, therapist, divorce financial planner, parenting coach, mediator, real estate and mortgage professional who specializes in divorce and maybe a lawyer
Stop burdening your family, friends, and children. Especially your kids, whether young or adult, don’t want to shoulder your divorce! If they are young or teens, you can create long-term damage for them. Your family and friends will be there for you, ask questions, call to check in, but they can not fix this for you and trashing your soon-to-be-ex is going to grow very old very fast.
Get organized. Gather your financial statements, tax returns, trust documents, will, insurance policies, business documents and financial reports. Put them in a safe place (electronically or physically).
Develop a plan. Do NOT pick up the phone and call a lawyer! You are setting yourself up for an unnecessarily miserable and expensive divorce. Call a divorce coach, a divorce financial analyst, a mediator. Make a plan to champion your divorce. It does not start with an attorney, even if eventually you need the services of a lawyer to deal with a contentious divorce.
You got this. It’s going to be hard but you can do it and you’ll be glad you took charge.
After reaching the decision to end a marriage, divorcing couples must do their best to set hard feelings aside and rationally deal with the division of household assets. But, turning attention toward your finances while processing the complicated emotions surrounding the end of a long-time partnership is oftentimes no easy task. Financial advice during your divorce is an important step towards you best outcomes.
The impact of a divorce on your finances is something that you should prepare for as you move from a double to a single-income household. Divorce often brings with it a change to both your income and expenses. TruNorth Divorce Solutions has put together a quick list of financial tips to set you up for post-divorce financial success.
1. Full disclosure and equitable division of property
Unless you have a prenuptial agreement in place, Maryland divorce law calls for an equitable division of joint assets. This doesn’t necessarily mean that property is divided 50/50 down the middle between spouses but instead, a fair settlement of all martial assets is sought. Any properties or assets owned prior to the marriage are considered non-marital assets and things like inheritances and gifts that were willed or given to a single partner are considered individual assets.
When you enter the divorce settlement process, financial transparency is a must. This type of honesty will help you and your soon-to-be-ex get through negotiations quicker. Having your finances outlined ahead of time cuts down on some of the leg work involved in the divorce mediation process. Getting accurate divorce financial advice means that both you and your ex will have an idea of what you own and what you owe.
2. Considering retirement accounts
One of the biggest mistakes a divorcing couple can make involves the splitting of retirement accounts. Some retirement plans also come with penalties for early withdrawals. If you are working with an expert in divorce finance, they can guide you through the process of drafting a qualified domestic relations order (QDRO) to shield your accounts from penalty. It’s also important to note that not all retirement accounts are governed by the same tax laws—a 401k is pre-tax money and treated differently than a pension plan just as the value of a Roth IRA differs from the already taxed value of the cash you have sitting in savings.
All this can make things muddy when it comes to dividing various accounts. Depending on how many jobs you have held during your marriage and whether you rolled them over as you’ve started a new position. Sorting through your retirement accounts can end up being a bigger undertaking than you might have anticipated. These are the types of financial details that are important to go over with a fine-toothed comb otherwise, things can easily slip through the cracks.
3. Additional tax considerations
If you are selling the marital home or dividing investment accounts, you must also consider the taxes involved in those sales. Stocks and ETF investments are subject to capital gains tax and the value of these accounts can go up and down over time—depending on the market. It could be a hard sell to divide these assets without selling them as you’d be gambling since it’s not possible to predict their future value, but that’s a bridge that you’ll have to cross when you get to it. Ultimately, whether or not you sell positions in your investment accounts or decide to divide them up will depend on the particulars negotiated during the settlement process.
Likewise some larger sales, like the family home, are subject to local tax laws. The state of Maryland has a 5.8% capital gains tax rate that applies to property sales—this means you’ll be looking at a capital gains tax of upwards of 30% (taking into account things like state and county transfer taxes).
4. Working with a Certified Divorce Financial Analyst
If you are seeking divorce financial advice, working with a Certified Divorce Financial Analyst® (CDFA®) or a CDFA®-Mediator is a great way to make sure that you leave no stone unturned when it comes to sorting through shared finances and dividing assets and debt appropriately. Weeding through your joint finances can be a particularly daunting task if you don’t have a solid background in finance and knowledge of tax law.
A divorce mediation financial consultant brings a certain level of financial expertise to the table and can relieve some of the stress associated with sorting through the particulars. Interested in learning more? Schedule a free strategy session.
The decision to divorce is never easy, but that doesn’t mean that settling your divorce needs to be complicated. Most modern divorces are seen as a division of shared property and the majority of today’s divorces never even enter the court system beyond the basic paperwork and procedure.
For individuals who are involved in uncontested divorces, mediation can be a quick and cost-effective alternative to working with a lawyer. But how do you go about divorce mediation, and what can you do to help smooth out the process? TruNorth Divorce Solutions offers a few divorce mediation tips to better set you up for success.
1. Consider divorce mediation
It’s not uncommon for couples involved in uncontested divorces to seek out divorce mediation services as an alternative to shelling out the big bucks for a family law lawyer. In Maryland (and across the United States), divorce mediation is quickly becoming a popular alternative to working with family law attorneys.
The most important divorce tip, once you’ve decided on mediation, is to the first step is to spend some time exploring your local options. Do your research so you know what to expect. A good mediator won’t mind answering questions about their professional experience, services, and metrics of success. Interviewing your mediator during your initial consultation can help you gauge your prospective mediator’s expertise and whether or not they fit your needs.
2. Don’t forget to consider the taxes
Some say taxes are one of the only two things you can’t escape in this life. One of the most common divorce settlement mistakes that divorcing couples make when selling and dividing joint assets—like retirement accounts and the family home—is that they don’t consider the taxes.
Failing to account for tax considerations when dividing marital assets can throw a major wrench into the system despite best intentions. Things aren’t always apples-to-apples and not all retirement accounts are governed by the same tax laws. An experienced divorce mediator can help navigate any tax issues that arise along the way, such as whether or not you need to get a Qualified Domestic Relations Order (QDRO).
3. Get your custody arrangements in writing
When it comes to divorce mediation tips, getting custody arrangements in writing is high on the list. Parents who don’t create a parenting plan ahead of time might get blindsided down the road and getting things in writing will help hold you and your soon-to-be-ex accountable. Taking the time to hash out your co-parenting schedule and expectations can help you avoid future hiccups when it comes to parental duties.
Remember, it’s important to remain flexible and treat your co-parenting plan as an adjustable framework. Schedules may change and dates might need to be shuffled around to accommodate that surprise business trip work sprung on you last minute. It’s a great idea to discuss your summer co-parenting plans yearly.
4. Consider your post-divorce budget
While not a mistake made during the mediation process, post-divorce budgeting is a topic worth touching on. Being realistic about your post-divorce budget is a crucial step for independent financial success.
Unless you were the sole breadwinner bringing that bacon to the table, your household income is going to decrease during the transition from a double to a single income household and your expenses often increase because they’re no longer shared. It’s important to assess your post-divorce finances and make adjustments to account for changes in income and expenses. Be sure to speak with a Certified Divorce Financial Analyst to help you plan for your future and make the best choices during your divorce.
These are just a few divorce mediation tips to help guide you through some of the pitfalls. Considering divorce mediation? Schedule a free strategy session online.
The relationship you have with your spouse is likely the most important connection in your adult life. At one time, not long ago, you were in love and could not imagine a life without them. You may have had children together, even grandchildren! But something shifted and now here you are contemplating or in the midst of a divorce. Hold on, because divorce is not for sissies.
Whether you initiated the split, or your spouse did, whether it was sudden or has been years in the making, this is among the most traumatic and life-changing events you’ll ever experience. Divorce permeates all aspects of our lives: emotionally, psychologically, financially, socially, and physically. I see the impact of separation and divorce on people’s lives every day in my practice as a divorce mediator, financial advocate, and coach.
I know it, too, because I’ve been there. Growing up, I was a child of divorce, and it fundamentally impacted my life. My mom didn’t get the emotional, legal, or financial support she needed after my father left her while pregnant with her fourth child. She never really recovered and that was terribly sad. As for me, it certainly dampened my remaining childhood years and, in some ways, still has adverse effects.
I also divorced the father of my own three young children many years ago now and went through the incredibly painful and expensive process of a litigated divorce. All I knew back then was to pick up the phone and call an attorney. What ensued were years of court battles and what today would amount to about $100,000 in attorney’s fees. I knew there had to be a better way.
Today, I am fully dedicated to assisting individuals and couples through the divorce process in a way that leaves them as unscathed as possible, so that they and their children can move on to build a better future without long-lasting trauma. Be clear, though, divorce is not for sissies and you will need support.
Financially, you may wonder how you’ll ever be able to support yourself and your children, how you’ll be able to afford to retire or live the life you’ve worked so hard for. Will you be able to keep your home? Will you have to get a better-paying job?
As a mom or dad, you will have to adjust to the reality that your children will be sharing their time with the other parent and, potentially, a new partner. I cried my eyes out the first Thanksgiving that my children spent with the father and his family five hours away. As prepared as I thought I was, I was still alone without the ones I loved the most.
You will worry what effect all of this will have on your children, whether young or adult. Don’t kid yourself that the kids seem to be just fine. They aren’t. They need you to be a full-time parent if they are young and empathetic to their changing lives no matter what the age.
Socially, you will lose many friends that you shared as a couple. Some of your friends may treat you differently, be wary of your stories and woes, or feeling awkward when you’re the only single person in a group of couples. As for intimate relationships, will you ever be able to love someone again, and how about dating, how is that going to work?
Emotionally and psychologically, you aren’t going to be yourself for a while. You may feel confused and overwhelmed, question yourself about even the smallest things, be less productive at work or at home, occasionally or often be emotionally volatile, anxious, and/or depressed.
Your health may suffer, too. You may eat or drink too much, skip routine, preventative care, not get enough exercise, and have difficulty sleeping.
All of this is completely normal. Divorce is not for the uninformed and it won’t go away if you put your head in the sand. The question is not whether you need support but what kind and from which sources. It will not all be okay if you just hire the right lawyer.
I am here to tell you: divorce is not for sissies! So, get informed, build your support team, and keep reading this blog—its mission is to give you the information you need and show you the way to making the right decisions for a brighter future for you and the ones you love.
If you’re reading this, then obviously you’re thinking about ending your marriage. Before you initiate your divorce, I’m going to ask you to take a few steps to ensure the best outcome for you should you decide to move forward. This is not a decision to be taken lightly and a little preparation can go a long way.
The reality for lots of couples that have invested in each other for many years is that if you’re going to end the relationship, you now have to stop thinking emotionally and start thinking financially.
#1 Evaluate What You Really Know About Your Finances
If your answer is anything but “Oh, I handle all our finances, I know exactly where we are,” then you have work to do. If you have been out of touch with your family finances for more than five years, don’t even try to get caught up. Get yourself to a CDFA® (Certified Divorce Financial Analyst) ASAP! You can find one in your area by going to the Institute for Divorce Financial Analysts. Do this BEFORE you tell your spouse you want a divorce. Your CDFA® will help you do a little digging to get some information before the information mysteriously disappears. They’ll also help you see what your financial life after divorce might look like.
#2 Gather Documents Before your Divorce Starts
This is the one thing you can do to save yourself a ton of money in the divorce process. Anything you can gather before you meet with either an attorney, a mediator, or a CDFA® will reduce the amount you ultimately have to spend out-of-pocket. Here a quick list of must-have documents.
3 years of tax returns
6 months of bank statements on all accounts
6 months of statements on each of your marital and separate investment accounts including 401k, deferred
compensation, ESPP, ESOP, 403b, 529, IRA, etc. If you are baffled by those different account types or you’re not
even sure if your spouse has a retirement plan, get to a CDFA® now!
Most recent 4 paystubs
Most recent mortgage statement on any properties owned
Copies of all insurance policies and annuities (the policies themselves as well as statements)
VIN numbers and mileage on vehicles owned
Most recent statements on debts, credit cards, car loans, etc.
Details of any business interests, e.g. S Corps, LLC’s, and partnerships
#3 Get Organized
Once you’ve gathered all the data, find a way to keep it all organized. Some people create a 3-ring binder with tables for each section, others put all their documents in a protected electronic environment like Dropbox, iCloud, or Google Drive. This is best when you need quick and easy access in a mobile format. Again, this will save you a lot of money down the road.
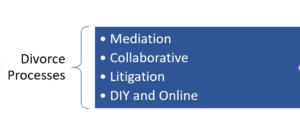
#4 Research Alternative Divorce Processes
There are several ways to get a divorce, each with its own pros and cons. Which method you choose will be largely dictated by the relationship between you and your spouse. If you are afraid for your or your children’s safety for any reason at all of it your spouse is denying you access to enough cash to survive, get a lawyer.
If you believe you and your spouse will be able to rationally discuss and negotiate the details of your divorce and be fair and honest, you might consider a do-it-yourself divorce or use an internet service to guide you. Beware: just because you and your spouse are getting along today doesn’t mean it will always be this way.
Your county’s divorce website will most likely give you an overview of the process and forms you’ll need if you going the DIY approach. There are lots of cheap internet services, too, that can produce divorce forms for your jurisdiction, but not all counties accept their forms as-is. These cheaper alternatives may seem attractive upfront but the money it may take to correct any mistakes you make along the way could cost you thousands of dollars.
If your financial situation is a bit more complex, e.g., there’s a pension involved or one party is self-employed, or the idea of DIY frightens you, then you should consider using a CDFA® as a financial neutral as part of a collaborative team or as a mediator to help you craft a fair settlement. Your CDFA® may also be able to get your legal documents prepared for you, too. When couples go this route, they are more likely to remain friends—it’s a respectful, honest way to go through the process and saves both parties significant money by not having to pay expensive lawyers.
As a last resort, if one or both parties can’t manage to cooperate at any level and seem determined to go to war, then hiring attorneys may be your only option. Unfortunately, you’ll need to say goodbye to about $15,000 per spouse, at a minimum. A little preparation before you move forward with a divorce can go a long way towards reducing the cost of your divorce and creating a fair settlement. Wishing you a gentle divorce and a bright future!
The divorce process can be scary and overwhelming. Starting with a plan and professionals that you trust to guide you through the process can be key in making sure you’re ready for your future. If you’re thinking about divorce schedule your complimentary divorce strategy session where we’ll explore your options and connect you with any resources you might need.